Stocks End Busy Week Higher

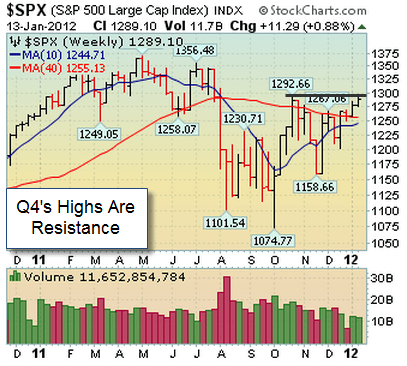
SPX- Q4's Highs Are Resistance

Friday, January 13, 2012
Stock Market Commentary:

Stocks and a slew of other risk assets ended the week higher shrugging off France’s downgrade (which made lose its AAA rating) and investors digested a slew economic and earnings data. From our point of view, the major averages confirmed their latest rally attempt on Tuesday 1.3.12 which was Day 9 of their current rally attempt. It was also encouraging to see the S&P 500 break above its downward trendline and its longer term 200 DMA line (shown above). Looking forward, the next area of resistance remains Q4’s highs (~1292) and then 2011 highs near 1370. In addition, the bulls remain in control as long as the benchmark S&P 500 trades above  its 200 DMA line.

Monday-Wednesday: Stocks Rally Ahead of EU Meeting

Stocks were relatively quiet on Monday as EU leaders met to discuss their debt problems and Alcoa officially kicked off Q4 earnings season. In Europe, French President Sarkozy and Germany’s PM Merkel met and said they want to complete their negotiations on a new treaty in the coming days so it could be signed by March 1, 2012. Meanwhile, Germany sold 3.9 billion euros ($4.9 billion) in six-month T-Bills with a negative yield for the first time in modern history. After the bell, Alcoa kicked off earnings season when they released their Q4 results. As always, it is very important to focus on how stocks react to earnings and not just the earnings. There have been many examples were the numbers are horrid but the stock gaps up and charges higher for the next few quarters and the converse is also true.
Stocks opened higher on Tuesday as Q4 earnings season kicked into gear. We also tell our clients that price is primary and everything else (even earnings) is secondary. Investors were also happy to see that for the second consecutive month, small-business optimism rose in the U.S. The National Federation of Independent Business Optimism Index rose to 93.8 in December which is 1.8 points higher than November’s reading and 5.7 points higher than September 2011. Elsewhere, wholesale inventories corrected in November to 0.1% which was down from October’s reading of +1.2%.
Stocks were mixed on Wednesday as the world awaited Thursday’s ECB meeting. In the U.S., a handful of companies released their Q4 results which largely met estimates. At 2pm EST, the Federal Reserve released its Beige Book which measures the economy at each branch in its 12 districts around the country. The Beige Book is released roughly two weeks before the next FOMC meeting and is used to gauge the overall health of the economy. The report showed that the U.S. economy grew albeit at a slower pace than Fed officials would like to see.

Thursday- Friday’s Action: ECB & BOE Meet, U.S. Economic Data Fails To Impress & France is Downgraded!

Before Thursday’s open, investors digested a slew of data. Overseas, The Bank of England held rates steady and said they would not print more money in the foreseeable future which was a backhanded vote of confidence for their economy. Meanwhile, the ECB also held rates steady which put pressure on European politicians to resolve their ballooning debt crisis. Spain and Italy both held successful bond auctions which helped alleviate short term refinancing fears. U.S. economic data failed to impress. First, weekly jobless claims topped estimates and rose by +24,000 to a seasonally adjusted 399,000 which was the highest level in six weeks and very close to the closely followed 400,000 mark. The four-week average also jumped to 381,750 from 374,000 in the prior week. Separately, the Commerce Department said retail sales rose +0.1% last month which fell short of the Street’s estimate for a gain of +0.3%. It was also the weakest reading in seven months. Finally, the Commerce Department said businesses inventories grew by +0.3% in November. Stocks slid on Friday after S&P cut several European nation’s credit ratings due to their ballooning debt.

Market Outlook- New Rally Confirmed

Risk assets (stocks, FX, and commodities) have been acting better since the latter half of December. Now that the major U.S. averages scored a proper follow-through day the path of least resistance is higher. Looking forward, one can err on the long side as long as the benchmark S&P 500 remains above support (1260). Leadership is beginning to improve which is another healthy sign. Now that the 200 DMA line was taken out it will be important to see how long the market can stay above this important level. If you are looking for specific help navigating this market, feel free to contact us for more information. That’s what we are here for!

Similar Posts

  • Week In Review: 7th Straight Weekly Gain on Wall Street

    STOCK MARKET COMMENTARY: FRIDAY, NOVEMBER 22, 2013 Stocks enjoyed their 7th consecutive week as the major averages continue to march higher. As we have mentioned several times recently, in the short-term the market is extended and a light volume pullback would do wonders to restore the health of this rally. So far, these pullbacks are…

  • Stocks End Volatile Week Higher

    Market Action- Confirmed Rally; Week 27
    It was encouraging to see the bulls show up and defend the major averages’ respective 50 DMA lines in November, January, and late February and early March. From our point of view, the market remains in rally-mode until those levels are breached. The tech-heavy Nasdaq composite and small-cap Russell 2000 indexes continue to lead evidenced by their shallow correction and strong recovery. If you are looking for specific high ranked ideas, please contact us for more information.
    Are You Looking For Someone To Manage Your Money?
    Our Private Wealth Management Services Can Help You!

  • Stocks Testing Support (2011 Lows)!

    Market Outlook- Rally Under Pressure:
    The major averages confirmed their latest rally attempt on Tuesday, August 23, 2011 which was the 11th day of their latest rally attempt. It is important to note that all major rallies in history began with a FTD however not every FTD leads to a new rally (i.e. several FTDs fail). In addition, it is important to note that the major averages still are under pressure as they are all trading below their longer and shorter term moving averages (50 and 200 DMA lines) and are all still negative year-to-date. Our longstanding clients/readers know, we like to filter out the noise and focus on what matters most: market action. This rally will fail if/when several distribution days emerge or August’s lows are breached. Until then, the bulls deserve the benefit of the doubt. If you are looking for specific help navigating this market, please contact us for more information.

  • Dow Hits New 2009 Closing High As Dollar Falls

    Stocks rallied across the globe as the dollar fell and the Dubai World concerns eased. Volume was lighter than Monday’s levels as the major averages advanced. Advancers trumped decliners by almost a 4-to-1 ratio on the NYSE and by a 2-to-1 ratio on the Nasdaq exchange. There were 45 high-ranked companies from the CANSLIM.net Leaders List making a new 52-week high and appearing on the CANSLIM.net BreakOuts Page, higher from the 13 issues that appeared on the prior session. New 52-week highs reported outnumbered new 52-week lows on the NYSE and on the Nasdaq exchange

  • Market's Edge Higher & Wait For Friday's Jobs Report

    The paper said Wednesday’s move in the Nasdaq composite marked a follow-through day for that index. We have received numerous emails and phone calls inquiring about the discrepancy in yesterday’s report. The simple fact is that the paper is using May 25, 2010 as Day 1 for the Nasdaq composite even though it closed lower on the day. From their perspective, the “essence of Day 1” occurred and that sufficed. It would be very encouraging to see a proper follow-through-day (FTD) emerge for the benchmark S&P 500 and the Dow Jones Industrial Average to confirm yesterday’s strong move. Now that we have a follow-through day, the window is open to begin buying high ranked stocks that trigger new technical buy signals. If you have any further questions on this matter, or would like to discuss your portfolio or the market, please feel free to email: info@sarhancapital.com.

  • Week-In-Review: Stocks Perched Near Record Highs As Earnings Season Begins

    Stocks Perched Near Record Highs As Earnings Season Begins The market was relatively quiet last week as earnings season officially began. The major indices remain perched below record highs as the bulls continue to dominate the landscape. The fact that there remains virtually no selling is a net positive for the bulls. In the short-term,…